130M Europeans already have access to a local Visa and Mastercard alternative
One step closer to payment sovereignty.
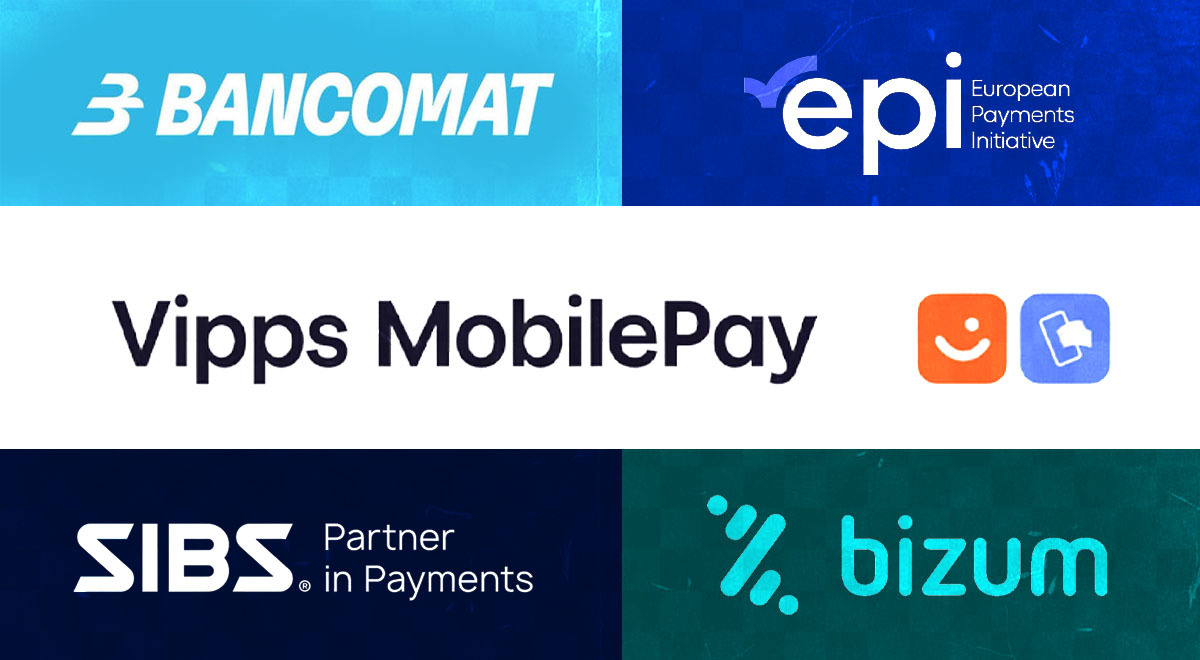
Image by Cybernews
 Follow us
- Five European companies formed the European Network for Payments to connect local payment systems across borders.
- More than 130 million users already have access through services in Italy, Spain, Belgium, Portugal, and Norway.
- The rollout will start with person-to-person payments before expanding to store and online payments.
- The project aims to reduce Europe’s reliance on Visa and Mastercard during geopolitical tensions.
Key Takeaways by nexos.ai, reviewed by Cybernews staff.
Five companies have partnered up to build an interoperable European Network for Payments, allowing millions of users to make cross-border payments.
Italy’s Bancomat, Spain’s Bizum, Belgium’s EPI Company/Wero, Portugal’s SIBS-MB WAY, and Norway’s Vipps MobilePay announced the creation of a new joint entity called the European Network for Payments on September 30th, 2026.
Participating systems will allow cross-border peer-to-peer, in-store, and online payments across Europe while preserving their respective brands and user experiences.
These services will be rolled out gradually, beginning with person-to-person payments.
Headquartered in Madrid, Spain, the new entity will connect participating payment solutions through a common technical and operational layer based on European standards.
Together, the participating solutions already cover approximately 130 million users across 13 European countries, giving them access to the interoperable network.
“The creation of this interoperability entity represents a significant step forward in building a sovereign and integrated European payments landscape,” Fabrizio Burlando, CEO of Bancomat, said in a statement.
Payments as geopolitical leverage
The European Network for Payments emerges as about two-thirds of Europeans support European tech alternatives to US payment systems.
International card schemes such as Visa and Mastercard accounted for over 60% of card transactions in the EU in 2022, according to data from the European Central Bank (ECB). These companies together handle 90% of global card payments, excluding China.
The consequences of such dependence could be dire if EU-US relations were to have a serious decline. A 2025 study doesn’t rule out that the US could restrict the operations of American payment networks that EU banks rely on.
The study draws on the precedent of Russian and Belarusian banks that were excluded from global payment networks in 2022 after Moscow invaded neighboring Ukraine.
“Payment systems can operate as instruments of geopolitical leverage, and that disconnection can occur rapidly and with far-reaching systemic effect,” the study suggests.
While the US’s sanctions on the EU or individual member states are difficult to imagine, the study's authors note that legal, institutional, and political mechanisms for doing so exist.
They argue that a digital euro, if widely adopted, would reinforce the EU’s monetary and technological sovereignty.
The ECB is working with the national central banks of the euro area to issue the digital euro, which the institution describes as a digital currency or “an electronic equivalent to cash.”
If approved by EU lawmakers and governments, the pilot rollout could begin in 2027, and the digital euro's full adoption could come as early as 2029.